
Key Takeaways
- Home protection involves both physical preparation and insurance readiness.
- Wind, water, flood, and maintenance-related damage may be handled differently under an insurance policy.
- Small maintenance tasks can reduce the chance of more serious storm damage.
- A current home inventory and organized records can make a claim easier to document.
- Safety comes first after a storm, followed by careful documentation and temporary measures to prevent further damage.
Storm preparation is not only about boarding windows or stocking batteries. It also means understanding the basics of homeowners insurance, keeping home records current, and knowing what to do if damage occurs. A little planning before severe weather arrives can reduce confusion during an already stressful situation.
A practical checklist turns a broad concern into manageable tasks. Homeowners cannot prevent every loss, but they can identify weak areas around the property, prepare their household for outages, and make it easier to respond when wind, water, falling limbs, or power failures affect the home.
Why A Home Protection Checklist Matters
Property damage often involves more than one problem at a time. Heavy rain can expose a roof issue, blocked gutters can send water toward the foundation, and a power outage can complicate cleanup. Reviewing the home before storm season helps homeowners address visible concerns while there is time to schedule safe, qualified repairs.
Regular preparation also creates a clearer record of the property’s condition. Photos of the exterior, receipts for repairs, and maintenance notes may help establish what the home looked like before an unexpected event.
When reviewing coverage, it can help to understand how property insurance may apply to the dwelling, belongings, and other covered structures. The specific protections, exclusions, deductibles, and limits will depend on the policy itself, so general information should never replace reading the contract carefully.
Step One: Check The Home’s Most Exposed Areas
Start with a ground-level walk around the home. Look for loose, curled, cracked, or missing shingles; clogged gutters; damaged siding; loose flashing; worn window seals; and exterior vents that need attention. Check whether downspouts carry water away from the foundation, and watch for signs of standing water, soil erosion, or leaks near doors and windows.
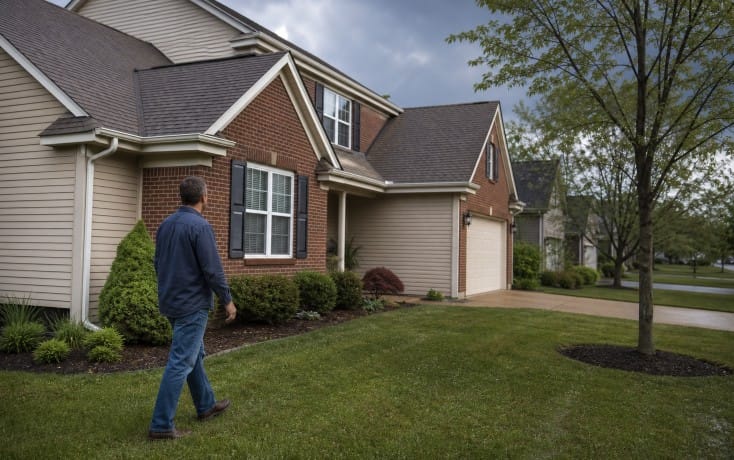
Tree care also matters. Dead limbs, branches rubbing against the roof, and trees leaning toward the home can become serious hazards in high winds. Secure or store outdoor furniture, planters, decorations, and grills before severe weather. Do not climb onto a roof or approach unstable trees after a storm. Roof repairs, electrical concerns, and hazardous tree removal are jobs for qualified professionals.
Step Two: Build A Simple Storm-Ready Kit
A small emergency kit can make an outage or evacuation more manageable. Keep it in a place that is easy to reach, and tailor it to the people, pets, and medical needs in the household. Basic emergency supply planning includes having enough essentials available when stores, roads, or utilities are temporarily inaccessible.
- Flashlights, extra batteries, phone chargers, and backup power banks.
- Bottled water and shelf-stable food.
- First-aid supplies, medications, and hygiene items.
- A battery-powered weather radio.
- Copies of identification, insurance details, and important contacts.
- Pet food, leashes, carriers, and other pet supplies.
Check the kit at least twice each year. Replace expired food and medication, test batteries, and update contact information. It is also wise to discuss where household members will meet and how they will communicate if phone service is limited.
Step Three: Review What The Policy Covers
A policy review should focus on more than the premium. Homeowners should confirm whether the dwelling limit reflects current rebuilding costs and whether personal belongings are settled at replacement cost or actual cash value. They should also check the deductible for wind, hail, hurricanes, or named storms, since it may differ from the standard deductible.
Questions To Ask During A Policy Review
- Are detached garages, sheds, fences, pools, or other structures included?
- What coverage is available for temporary living expenses if the home is unsafe?
- Are jewelry, art, collectibles, tools, or electronics subject to special limits?
- Does a home-based business or short-term rental activity create an exclusion?
- Which losses are excluded because of wear, poor maintenance, earth movement, or other causes?
Flood And Water Damage Need Special Attention
Not all water damage is treated the same way. Water entering through a storm-damaged roof may be evaluated differently from a plumbing leak, sewer backup, or rising floodwater. In particular, most standard homeowners’ policies do not cover flooding, so homeowners should understand whether separate flood protection or a water-backup endorsement may be relevant to their situation. Waiting periods can apply to some policies, making last-minute decisions risky.
Step Four: Create A Home Inventory That Actually Helps
A useful inventory does not have to be complicated. Walk through each room and take photos or short videos of furniture, appliances, electronics, clothing, tools, sporting goods, and items in closets or storage areas. Record brand names, model numbers, serial numbers, purchase dates, and estimated values when available.
Save receipts, warranties, appraisals, renovation invoices, and repair records with the inventory. Keep digital copies in secure cloud storage or another location outside the home. Update the file after major purchases, remodeling work, or significant changes in household possessions.
Step Five: Prepare For A Claim Before One Happens
- Prioritize safety. Evacuate if officials direct it or if the structure appears unsafe.
- Prevent additional damage when safe. Cover a broken window or move belongings away from an active leak.
- Document the loss. Take wide photos and close-up images before cleanup whenever conditions allow.
- Report the damage promptly. Keep the claim number and note the date, time, and names involved in each conversation.
- Save receipts. Retain proof of temporary repairs, cleanup supplies, lodging, and other related expenses.
- Keep damaged property when practical. Do not discard items before inspection unless they create a health or safety hazard.
Be alert for storm-related repair scams. Verify licenses when applicable, request written estimates, avoid high-pressure sales tactics, and read any assignment-of-benefits agreement before signing. Permanent repairs should generally be coordinated with the insurer when possible, while reasonable temporary measures may help prevent further damage.
What To Do After A Storm
Wait until authorities or utility providers indicate that the area is safe. Watch for downed power lines, gas smells, unstable ceilings, standing water near electrical outlets, and damaged trees. Inspect the attic, ceilings, windows, basement, and exterior walls from safe locations, looking for stains, damp insulation, odors, bubbling paint, or other signs of water intrusion.
A Seasonal Home Protection Schedule
- Monthly: Check for leaks, test smoke alarms, and look for new roof or siding damage.
- Spring: Clean gutters, inspect trees, and review emergency supplies.
- Summer: Review severe-weather plans and update household contact information.
- Fall: Clear leaves, inspect drainage, trim weak branches, and refresh the home inventory.
- Winter: Protect pipes, service heating equipment, and prepare for freezing-weather outages.
Conclusion
Good home protection is built through small actions completed before trouble starts. A careful inspection, current records, a basic emergency kit, and a thoughtful policy review can make a difficult situation easier to manage. The most effective checklist is one that is updated regularly and kept within easy reach.